Lonvest Review 2026: My Hands-On Test at 13.5% Interest
My hands-on Lonvest test has begun. I deposited and invested my own money, and I’m documenting step by step how the platform performs in everyday use.
My verdict in 30 seconds: My first impression is good: The platform is easy to navigate, my deposit arrived in less than 24 hours, and investing takes just a few clicks. So far, I’m especially impressed with how user-friendly it is. Support has also made a good impression so far and usually responds quickly in the investor chat. I’m more cautious about safety and risk, partly because there is no specific P2P/investment regulation and the track record is still comparatively short. My long-term test is also only just getting started.
My Lonvest rating: 75 out of 100 points
This rating is deliberately provisional. I’ve already been able to test deposits, navigation, and the investment process firsthand. I’ll add updates on repayments, maturities, and a withdrawal of my own as the test progresses.
What is Lonvest?
Lonvest is a P2P/P2P-adjacent investment platform based in Croatia and part of the SpaceCrew Finance Group ecosystem. Investors use the platform to invest in loan portfolios from lenders within the group. Lonvest has been active since 2023 and now has more than three years of platform history. According to Lonvest, there have been no delays in payments to investors during this time. The SpaceCrew Finance Group behind the platform says it has operated in fintech for ten years and served more than two million customers worldwide. In its 2025 Management Report, the group reports revenue of around US$45 million and approximately US$125 million in loans issued. In 2026, Lonvest offers investments from Malaysia and Singapore, among other markets. SpaceCrew Finance has also expanded into South Africa and Colombia. According to Lonvest, investment opportunities from these markets are expected in Q1 2027.
I’m particularly interested in the international focus. Many P2P portfolios are heavily concentrated in Europe. Loans from Malaysia add a different geographical component to a portfolio, at least—but that’s no substitute for a proper risk assessment.
My experience with Lonvest so far
I had already registered with Lonvest before my current test. I remember the registration and verification process as straightforward. In September 2026, I wanted to take another closer look, so I deliberately started with just €50.
For now, this is a test run. If deposits, investments, repayments, and later withdrawals all work reliably and the loan offering remains attractive, I could certainly see myself expanding my portfolio on Lonvest. Bonus or cashback promotions in particular could give me a reason to invest a larger amount.
Deposit: surprisingly fast
On September 24, 2026, at around 1:30 p.m., I sent €50 to Lonvest via a regular SEPA transfer from my Kreissparkasse. My bank didn’t offer an instant transfer.
Lonvest’s email arrived as early as September 25 at 9:37 a.m.: The €50 had been credited to my account. So the deposit took less than a day. In my view, that’s a very good start for a regular SEPA transfer.
Investing in just a few clicks
What I really like is how simple the investment process is. Lonvest describes it, in effect, as “Invest in a few clicks”—and that’s exactly how it felt during my test.
- Choose the investment amount or click “Max.”
- Choose a country.
- Set the term.
- Accept the terms of use.
- Invest.
No unnecessary clicking through dozens of individual loan offers. The position then appears clearly under “My Investments,” along with the purchase date, end date, interest rate, investment amount, term, and status.
Malaysia at 13.5%: especially appealing right now
The Malaysia loans were one of the reasons I decided to take a closer look at Lonvest again. The offer is backed by AmanahKredit, or the Malaysian company Constance Infinity Sdn. Bhd. Other P2P bloggers have also reported on the expansion of the Malaysia business.
The special offer I used, with 13.5% p.a., is advertised in the dashboard with “Invest by 1 October.” If you’re interested, check the terms currently shown directly on Lonvest—promotions and interest rates can change.
Lonvest by the numbers: current status in September 2026
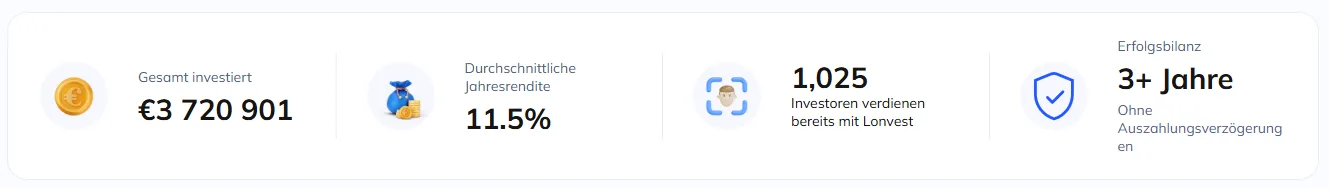
Lonvest currently shows around €3,720,901 in total invested capital, an average annual return of 11.5 % and 1,025 investors with active investments. The platform also advertises a track record of more than three years without payment delays. Important: These figures come from Lonvest itself and have not been independently verified by me.
Malaysia and Singapore: interest rates by term
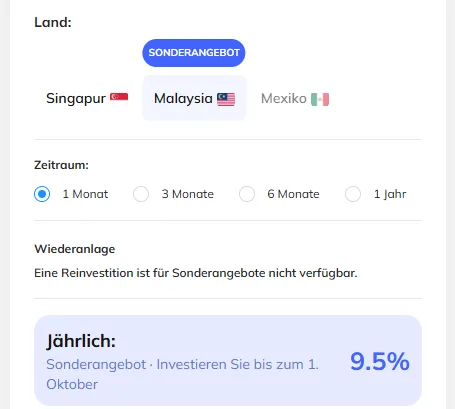
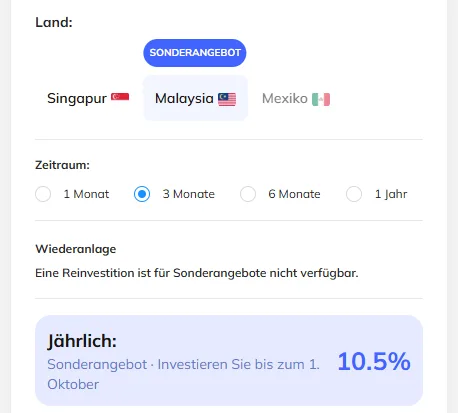
I find it interesting that I can choose the term myself. At the end of September 2026, the following annual interest rates were shown for Malaysia and Singapore:
| Term | Malaysia | Singapore |
|---|---|---|
| 1 month | 9.5 % | 9.0 % |
| 3 months | 10.5 % | 10.0 % |
| 6 months | 11.6 % | 11.0 % |
| 1 year | 13.5 % | 13.0 % |
For my €50 test, I chose Malaysia and a one-year term. With a larger amount, I’d weigh the additional return more carefully against the longer period my capital would be tied up. The Malaysia special offer was marked in my account as “Invest by October 1”; terms and promotions can change.
Loyalty program: gets more interesting at €10,000
The current loyalty program has four tiers and becomes available only after 90 days on the platform. Below €10,000, the standard interest rate applies. An active portfolio of €10,000 qualifies for Sapphire: +0.5 percentage points; at €25,000, it’s +0.75 percentage points (Emerald), and at €50,000, it’s +1.0 percentage point (Diamond).
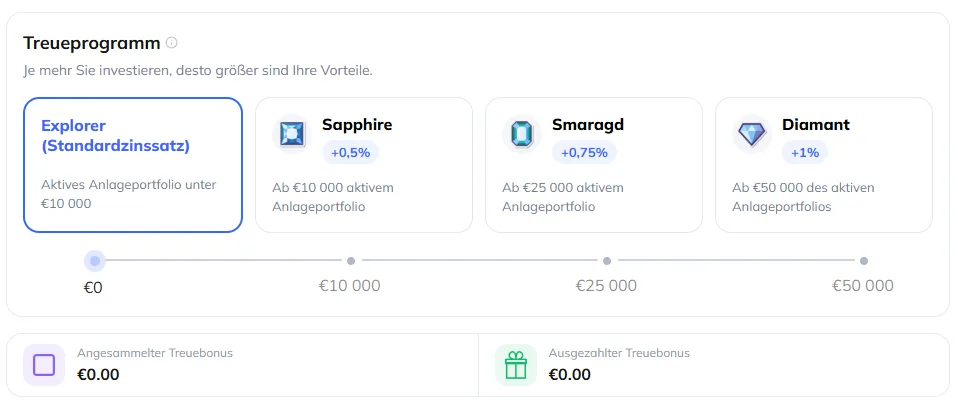
The €10,000 tier would generally be a realistic amount for me. Even so, I don’t want to add funds just for the bonus. First, I want to gain more firsthand experience with repayments, maturities, and eventually a withdrawal.
1% cashback for new investors?
The partner information I have states that newly referred investors receive 1% cashback on investments made during the first 90 days after registration. That’s attractive, but I’d check the currently applicable terms again before registering, since bonus programs can change.
What would make me invest a larger amount?
My short test has gone well so far: Despite using a regular SEPA transfer, the €50 arrived in my account in less than 24 hours, and investing it afterward took just a few clicks. I like that simplicity.
For a larger amount, what I’d like most is a broad selection of investments, competitive interest rates, and occasional cashback promotions. A substantial, time-limited bonus could certainly give me a reason to expand my investments on Lonvest sooner. At the same time, the larger the investment, the more important diversification and platform risk become.
I also don’t want to invent disadvantages just to make a pros-and-cons list longer. In my hands-on test so far, I simply haven’t noticed anything seriously negative. The real test comes with time: repayments, maturities, and the withdrawal test later on.
Auto-invest: simple, but with less control
Lonvest primarily uses automated allocation. You set details such as the amount, country, and term; the platform handles the specific allocation. That’s convenient and fits the very simple user experience.
The downside: Anyone who wants to analyze and select every loan individually has less control than on traditional marketplaces. That’s not a dealbreaker for me right now, but it belongs in a transparent review.
Early Exit: accessing my money early
Lonvest doesn’t have a traditional secondary market, but it does offer Early Exit. I’ve now tested it myself: For my active 365-day investment, I was able to simply click “Cancel” under “My Investments.” Lonvest clearly warned me beforehand that I would lose 100% of the interest accrued up to that point if I ended the agreement early. That was completely fine for my test—I mainly wanted to find out whether exiting actually worked.
I then had to confirm the action using my Google Authenticator code. After that, Early Exit worked without any problems. I think that’s great: If I need liquidity at short notice, I don’t necessarily have to wait until the end of the term. The trade-off is losing the interest accrued up to that point. I also like that Lonvest requires another two-factor authentication step to confirm the cancellation.
Refer friends: 1% cashback up to a maximum of €1,000
Lonvest also has a referral program. The dashboard currently advertises that referred investors can receive 1% cashback on the amount they invest, up to a maximum cashback of €1,000. Check the specific terms in your account before participating.
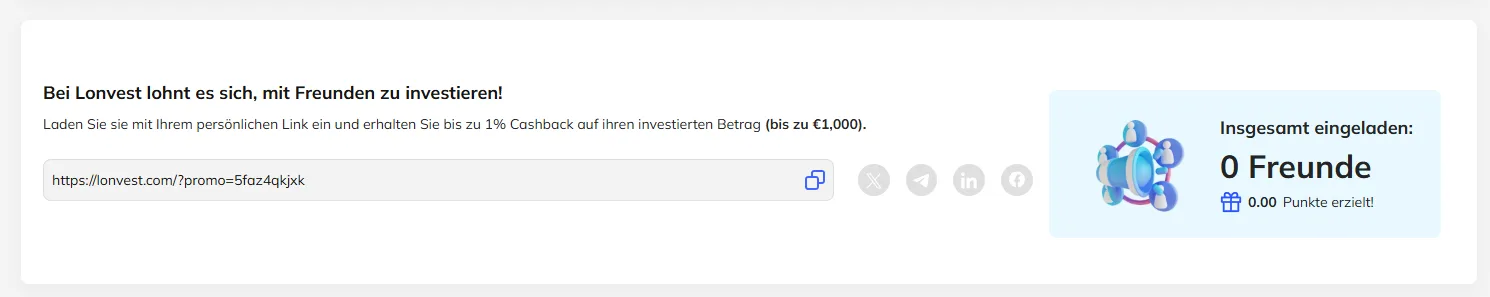
This could certainly be interesting for active P2P investors. I’ll also keep an eye on whether Lonvest launches additional limited-time cashback campaigns in the future. Personally, promotions like these would be a much stronger incentive for me to increase my investment.
Tax documents: a practical solution
I also appreciate that Lonvest provides documents or information for tax returns in the account. When you use several P2P platforms, having proper documentation at the end of the year is worth its weight in gold.
Support and investor chat: notably quick so far
I’ve also been impressed by the Lonvest Investor Chat. At the end of September 2026, it had around 217 members. For several questions I followed, replies often came within about 10 to 30 minutes, and sometimes within just a few minutes. Of course, that’s not a guaranteed response time. I haven’t had to resolve a support issue of my own yet, but the visible activity supports a high support rating for my first impression.
What do I like about Lonvest so far?
- Early Exit successfully tested by me: I was able to end my active investment early. The capital was released; in return, I gave up the interest accrued.
- Extra security: I had to confirm Early Exit again using Google Authenticator.
- Very clean user interface and available in German.
- Fast deposit: In my test, the money arrived the next morning.
- Simple investing without unnecessarily complicated loan selection.
- Attractive interest rate: My Malaysia test investment earns a nominal 13.5% p.a.
- Loyalty program for larger portfolios.
- Referral program and potential special offers.
- Clear dashboard with all the key investment details.
What do I like less—and what are the risks?
So far, I personally haven’t experienced any specific negative incidents. Still, it would be wrong to infer that an investment is safe just because the deposit was fast and the user interface worked well.
- Younger platform: Lonvest has been on the market since 2023. According to the company, there have been no delays in investor payouts during its more than three years of operation so far.
- No traditional P2P regulation or deposit protection: Investors bear the risk of default.
- Group concentration: The platform and lenders are economically tied to the same corporate group.
- Bullet repayment for longer-term investments: Depending on the product, principal and interest may not be returned until the end of the term.
What other P2P bloggers are saying about Lonvest in 2026
The picture in the German-speaking P2P community is quite interesting. P2P-Anlage reports a considerably expanded Lonvest portfolio of its own and particularly highlights Malaysia and the loyalty program. Rethink P2P views the simple automation positively, but points to the lack of regulation, the still-short track record, and the absence of audited consolidated financial statements as risk factors.
There are also more critical voices. P2P-Macher ended its Lonvest investment in 2025 and criticized, among other things, transparency, interest rate changes, and product developments that were delayed at the time. Some of these points have changed in 2026—Malaysia is now actually available—but the fundamental questions around transparency and group concentration remain relevant.
What I like—and what I’m keeping an eye on
| What I like | What I’m keeping an eye on |
|---|---|
| Very simple, German-language interface | My own test period is still short |
| Deposit arrived in less than 24 hours | Early Exit successfully tested by me; interest is forfeited |
| Attractive interest rates and different terms | Higher interest rates mean capital is tied up for longer |
| Loyalty program and promotions | Platform and group concentration |
| Active investor chat | Still need to test a withdrawal myself |
My Lonvest verdict for 2026
My first real-world test has been positive so far. Lonvest feels much more mature and interesting to me than it did some time ago. The platform is clear, available in German, and investing is pleasantly straightforward. My €50 deposit was credited in less than 24 hours, and a few minutes later I was able to invest the money in Malaysia at 13.5% p.a.
But this is only the beginning of my test. What I’m especially interested in is how reliably repayments work, how the Malaysia offering develops, and whether Lonvest launches more bonus or cashback promotions. If so, I could see myself making a larger investment.
For now, Lonvest remains on my watchlist, with real skin in the game. I’ll update this review as soon as there are new repayments, promotions, or other relevant experiences to report.
Personal investment: €50 · Malaysia · 13.5% p.a. · Term ends September 25, 2027
Note: This post describes my personal experience and is not investment advice. P2P investments involve significant risks, including the total loss of invested capital. Interest rates, bonus programs, and terms can change at any time. Affiliate links may be included; they won’t cost you anything extra.

No Comments found